 Construction is the only industry where a company can have $2M in signed contracts, a full crew working, and no cash to make payroll on Friday. The billing cycle doesn't align with the payroll cycle. Retainage withholds 10% of every dollar earned. Owners pay 30–45 days after billing. Subcontractors need payment before the GC receives it. Material suppliers want payment before the work is billed. Every one of these timing mismatches is manageable — but only if you can see them coming.
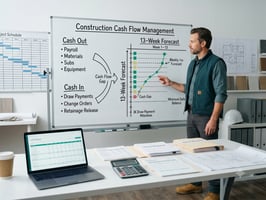
The 13-week cash flow forecast is the most important financial management tool available to a construction company. It shows, week by week for the next 90 days, exactly what cash will come in, what cash will go out, and what the resulting bank balance will be. A forecast that shows negative cash in week 9 gives the company 9 weeks to take action — draw on the line of credit, accelerate billing, defer non-critical spending, or close a new project to improve inflows. The same problem discovered in week 9 produces a crisis.
Annual budgets and quarterly financial statements are too coarse for construction cash flow management. A project that's on budget in Q2 can still generate a cash crisis in week 7 of Q2 if billing timing and payroll timing collide wrong. The 13-week horizon is short enough to be accurate and long enough to enable action.
Construction time tracking software feeds the forecast's most critical output variable: the weekly payroll outflow. When hours from the construction timesheet app are available by week, actual payroll cost can be projected with precision rather than estimated from headcount assumptions.
Why 13 Weeks?
13 weeks = one calendar quarter. Long enough to capture meaningful patterns — billing cycles, payment receipts, seasonal cash flow — short enough that projections remain accurate.
Beyond 13 weeks: Too many variables change — projects start and finish, change orders shift billing amounts, owner payment behavior varies. 14-week projections are false precision.
Inside 4 weeks: Not enough horizon to take meaningful action. By the time a cash problem is visible in week 2, week 1 has already happened.
13 weeks is the practical window where:
- Labor payroll projections are based on real schedule data — not guesses
- Billing applications can be planned with specificity
- Sub payment timing reflects actual contract terms
- Line of credit draws can be planned rather than reactive
The Two Sides of the Forecast
Every week in the forecast has two sides: cash in and cash out.
Cash Inflows
Owner payments (progress billing) The primary inflow. The collection pattern:- Application submitted by the 25th of the month (or contract-specified date)
- Architect reviews and certifies — typically 7–14 days
- Owner pays certified amount — typically 14–21 days after certification
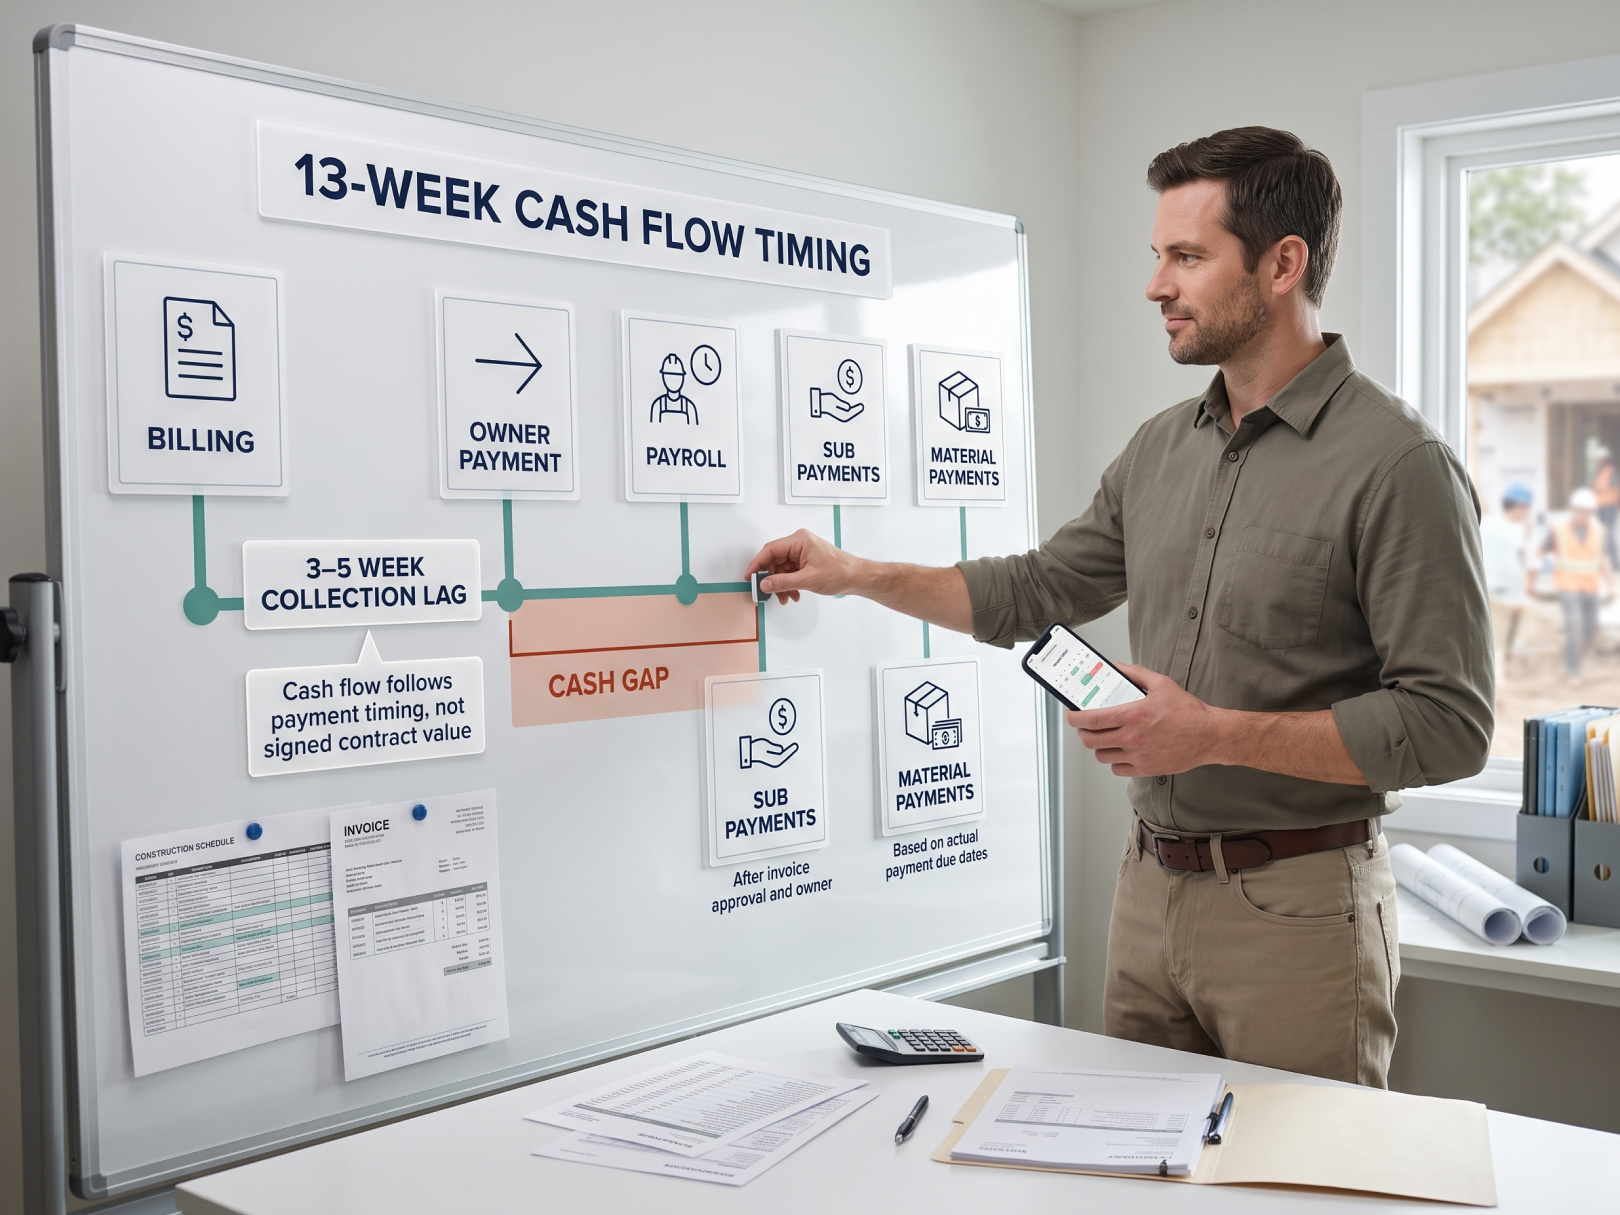
- Net: payment received approximately 3–5 weeks after application submitted
For a monthly billing cycle, the forecast must stagger billings and collections accurately. Application submitted week 4 → certification week 6 → payment received week 8. This 4-week lag between billing and collection is the primary driver of construction cash flow tension.
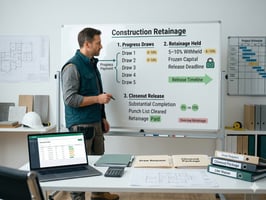
Retainage releases Retainage held throughout the project is released at substantial completion (typically) or in portions as the contract specifies. A project with 10% retainage on $2M of work has $200,000 sitting with the owner that doesn't appear until closeout. Forecast retainage release timing accurately — it's a significant inflow event.
Change order payments Approved change orders added to the billing application flow through the same billing/collection cycle. Pending (unapproved) change orders should not appear as inflows until approved. Optimistically including pending COs in the inflow forecast is a common cash flow planning error.
Bond and insurance claims Rare but significant. If applicable, include expected recovery timing.
Line of credit draws When the forecast shows a cash gap, planned line of credit draws appear as inflows in the week they're needed. Better to plan the draw in advance than discover the gap on Thursday of the same week.
Cash Outflows
Payroll (largest and most predictable) Weekly payroll is the most consistent outflow in construction. Amount varies with hours worked, but with a crew of known size working a defined schedule, weekly payroll is projectable with high accuracy.Construction crew time tracking feeds this projection: Hours in the contractor time tracking app by week, multiplied by fully burdened labor rates, give the actual projected payroll outflow for each week — not a headcount estimate. As the week progresses and hours accumulate, the projection becomes actuals. The forecast updates in real time.
Payroll taxes: FICA employer match, FUTA, SUTA deposit timing follows IRS and state schedules. Semi-weekly depositors must deposit within 3 business days of payroll. These deposits appear in the forecast 2–3 days after payroll.
Subcontractor payments Sub payment timing depends on the subcontract:- "Pay when paid" provisions: GC pays sub after receiving owner payment — typically 7 days after receipt per many state laws
- Payment cycle: Sub invoices approved, payment issued per the payment cycle agreed in the subcontract
Forecast sub payments based on:
- Sub billing dates (when subs submit invoices)
- GC review and approval time (7–14 days)
- Payment timing per subcontract (Net 7 after owner payment receipt, or Net 30 from invoice)
On a project where the GC receives owner payment in week 8, sub payments may be due week 9 or 10 — depending on contract terms. This creates a 1–2 week bridge between receipt and disbursement that must be funded.
Material purchases Material suppliers typically offer net 30 terms. Order placed week 1 → delivery week 2 → payment due week 6 (30 days from delivery). Forecast the payment week, not the order week.Large purchases: A major structural steel delivery may be $350,000 — forecast this as a specific week event, not averaged into weekly material outflow.
Equipment — owned and rented- Rented: Invoice typically monthly; forecast payment per invoice due date
- Owned: Operating costs (fuel, maintenance, repair) — estimate weekly or monthly and distribute
- Equipment purchases: Single-event outflows — major equipment acquisitions appear as specific week items
- Office rent: typically due 1st of month
- Insurance premiums: monthly, quarterly, or annual — forecast the actual payment dates
- Utilities, phones, subscriptions: monthly
- Vehicle payments or leases: monthly
- Loan and line of credit payments: per loan schedule
- Workers comp: monthly installments in most states
- Health insurance: monthly premium, often due 1st of month
- 401(k) contributions: typically within 7 business days of payroll
- Union fringe remittance: monthly, typically due by the 15th of the following month
Building the 13-Week Forecast: Step by Step
Step 1: Set Up the Template
WEEK NUMBER: 1 2 3 4 5 6 7 ... 13 WEEK STARTING: [Date][Date][Date][Date][Date][Date][Date] ... [Date] OPENING BANK BALANCE: $[X] CASH INFLOWS: Owner Payment - Proj A Owner Payment - Proj B Retainage Release - Proj C CO Payment - Proj A Line of Credit Draw Other TOTAL INFLOWS: CASH OUTFLOWS: Payroll - Direct Labor Payroll Taxes (FICA/etc.) Subcontractor - MEP Sub Subcontractor - Framing Sub Subcontractor - [Other] Materials - Proj A Materials - Proj B Equipment Rental Overhead - Rent/Utilities Insurance (WC, GL) Benefits / 401k Loan Payments Other TOTAL OUTFLOWS: NET CASH FLOW: (Total Inflows − Total Outflows) CLOSING BANK BALANCE: (Opening Balance + Net Cash Flow) The closing balance of week N is the opening balance of week N+1. The closing balance column is the output that drives decisions.
Step 2: Populate the Opening Balance
Start with the actual current bank balance — not accounting balance, not receivables. Cash available today. If the line of credit has an outstanding balance, note it separately — the line balance is not available cash, it's debt capacity.
Step 3: Project Inflows
For each active project:
- Pull the billing application schedule — when is the next application due? When is the application after that?
- Apply the collection timing model: billing date → certification period → owner payment period
- Enter the expected payment amount in the week of expected receipt
For retainage:
- Identify which projects are approaching substantial completion within the 13-week window
- Estimate retainage held by project (retainage % × billings to date)
- Enter expected retainage release in the appropriate week
Be conservative on inflows. Owners pay late more often than they pay early. If the contract says 30 days and the owner has paid in 38–42 days, use 42 days in the forecast.
Step 4: Project Payroll Outflows
Pull the weekly hour projection from the construction time keeping software:
- Current week: actual hours accumulated to date, projected hours for remaining days
- Future weeks: scheduled crew size × hours/day × days/week
Multiply by fully burdened labor rate:
Week 5 payroll projection: 10 workers × 40 hours × $46.11 burdened = $18,444 Payroll taxes (employer): $18,444 × 7.65% = $1,411 Workers comp: $18,444 × 12% = $2,213 Total week 5 payroll outflow: $22,068 For union labor, add fringe contributions:
Fringe: 10 workers × 40 hours × $21.15 = $8,460 Total with fringe: $30,528 GPS time tracking data feeds forecast accuracy: When actual hours from the GPS-verified construction employee time tracking app replace projected hours as weeks progress, the forecast updates with real data. By mid-week, actual payroll cost for the current week is knowable — not estimated.
Step 5: Project Subcontractor Payment Outflows
For each major subcontractor:
- When is their next invoice due from them?
- When will the GC approve it?
- When is payment due under the subcontract terms?
Enter the expected payment amount in the week it will be paid. For "pay when paid" provisions, tie sub payment timing to the week the GC receives owner payment — typically 1 week after receipt.
Step 6: Project All Other Outflows
- Material purchases: When are payments due (30 days from delivery date)? Enter by specific purchase.
- Equipment rentals: Monthly invoice amount ÷ weeks, or specific invoice due dates
- Fixed overhead: Actual due dates for rent, insurance, utilities, loan payments
Step 7: Calculate Weekly Net and Running Balance
Week 5 example: Opening balance: $124,500 Total inflows: $183,000 (owner payment received) Total outflows: $198,400 (payroll + sub payments + materials) Net cash flow: ($15,400) Closing balance: $109,100 Week 6:
Opening balance: $109,100 Total inflows: $12,000 (small CO payment) Total outflows: $187,200 (payroll + materials + overhead) Net cash flow: ($175,200) Closing balance: ($66,100) ← CASH CRISIS IN WEEK 6 A negative closing balance is a cash crisis — but seen 6 weeks in advance, it's a manageable problem. Draw on the line of credit in week 5 before the balance goes negative. Accelerate the week 7 billing application to pull the collection into week 10 rather than week 11.
Warning Signs in the Forecast
Negative balance week: Requires immediate action — line of credit draw, billing acceleration, or outflow deferral.
Balance trending down 3+ consecutive weeks: Even if not yet negative, a consistent decline signals the billing/collection cycle is out of sync with the outflow cycle. Investigate the cause.
Large single-week outflow with no matching inflow: A major sub payment or material delivery due in a week with no owner payment receipt. Plan in advance — don't find it in real time.
Retainage gap: Multiple projects approaching closeout simultaneously can create a retainage collection spike if the GC isn't billing for it. And if the GC is waiting on sub punch list to release retainage, cash sits uncollected.
Slow owner payments: If actual owner payment receipts are consistently 1–2 weeks later than the forecast projects, adjust the collection timing model. A systematically optimistic inflow forecast produces systematically incorrect balance projections.
Managing Cash Flow Gaps
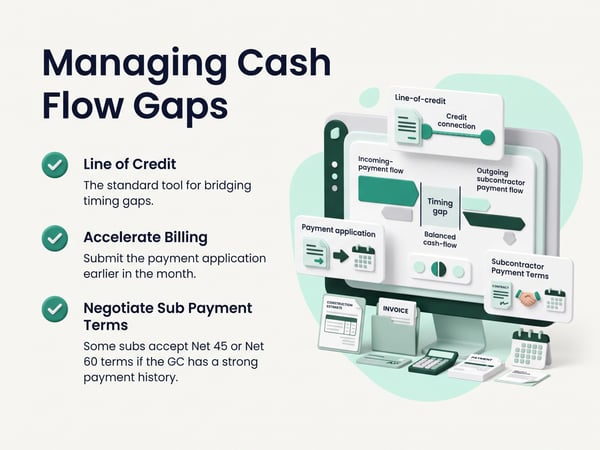
Line of credit: The standard tool for bridging timing gaps. A $500,000 revolving line of credit covers the 4–6 week gap between billing and collection. Draw when the forecast shows a gap approaching; repay when the owner payment arrives. The line of credit should be established before it's needed — not applied for during a cash crisis.
Accelerate billing: Submit the payment application earlier in the month. Move the application date from the 25th to the 20th and gain 5 days on the collection timing. Not always possible under the contract, but worth checking.
Negotiate sub payment terms: Some subs accept Net 45 or Net 60 terms if the GC has a strong payment history. Extending sub payment timing improves the GC's cash flow window.
Reduce retainage: Many contracts allow retainage reduction to 5% at 50% completion. Request this actively — the owner doesn't initiate it. A 5% reduction on $500,000 of completed work releases $25,000 in previously withheld cash.
Front-load the schedule of values: Higher values on early-completing items improve early-project cash flow. Negotiate this at contract execution — don't wait until the first billing application.
Multi-Project Cash Flow Aggregation
A company running 5 simultaneous projects needs a consolidated 13-week forecast — not 5 separate project forecasts.
Consolidation process:
- Build individual 13-week forecast for each project
- Sum all project inflows by week — consolidated inflow column
- Sum all project outflows by week — consolidated outflow column
- Add company-level overhead (not allocated to specific projects) as outflows
- Opening balance = total company cash, not project-specific cash
The consolidated forecast shows which weeks the portfolio generates cash vs. consumes it — and whether strong billing weeks on one project can offset slow collection weeks on another.
Cross-project cash dependencies: On a "pay when paid" basis, if Project A owner is paying late, the Project A sub may not get paid on time. If that sub is also working on Project B, the payment delay on A may affect their willingness to mobilize fully on B. The consolidated forecast makes these dependencies visible.
Common Forecasting Mistakes
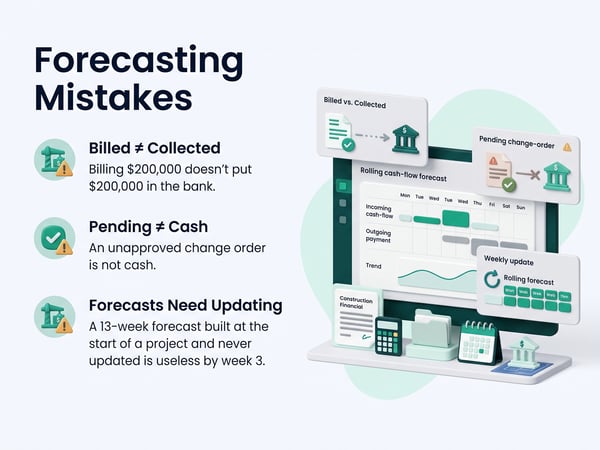
Using billed amounts instead of collected amounts Billing $200,000 doesn't put $200,000 in the bank. Collection timing — typically 4–6 weeks after billing — is the number that matters for cash flow.
Including pending change orders as inflows An unapproved change order is not cash. Include approved COs only. Pending COs may never get approved, or may be approved at a different amount.
Not updating weekly A 13-week forecast built at the start of a project and never updated is useless by week 3. Update every week — roll the horizon forward, replace projections with actuals for past weeks, adjust future projections based on what changed.
Optimistic collection timing If the contract says Net 30 but the owner consistently pays in 42 days, model 42 days. Systematic over-optimism on inflows produces systematic cash balance overstatement.
Missing fringe and payroll tax outflows Labor payroll is the gross wages. The actual cash out also includes FICA employer match, workers comp installments, fringe remittance, and health insurance. Forecast the total, not just gross wages.
Not planning the line of credit draw in advance A line of credit drawn 3 days before a bounced paycheck is a crisis. A line draw planned 6 weeks in advance based on the forecast is financial management.
13-Week Cash Flow Forecast Template
COMPANY: [Name] FORECAST PERIOD: [Start Date] — [End Date] PREPARED: [Date] PREPARED BY: [Name] Wk1 Wk2 Wk3 Wk4 Wk5 Wk6 Wk7 Wk8 Wk9 Wk10 Wk11 Wk12 Wk13 OPENING BALANCE: INFLOWS: [Project A] Owner Pmt [Project B] Owner Pmt [Project C] Owner Pmt Retainage Releases Change Order Payments LOC Draw (planned) Other TOTAL INFLOWS: OUTFLOWS: Payroll — Direct Labor Payroll Taxes (FICA) Payroll Taxes (FUTA/SUTA) Workers Comp Installment Health/Benefits/401k Fringe (Union, if applicable) [Sub A] Payment [Sub B] Payment [Sub C] Payment Materials — [Project A] Materials — [Project B] Equipment Rental Office Rent General Liability Insurance Vehicle/Equipment Payments Loan Payments LOC Repayment Misc Overhead TOTAL OUTFLOWS: NET CASH FLOW: CLOSING BALANCE: LOC OUTSTANDING: AVAILABLE CREDIT: Related Resources
TaskTag Features
- GPS Time Tracking for Construction — GPS-verified weekly labor hours that feed weekly payroll outflow projections
- Construction Time Tracking Software — real-time hours data converting payroll estimates to actuals in the forecast
- Time Tracking for Construction Workers — worker-level hours for accurate weekly payroll cost projection
- Top 5 Construction Time Tracking Apps — apps with weekly hour exports for cash flow forecasting
- Top 5 BusyBusy Alternatives — alternatives with payroll integration for cash flow management
- TaskTag vs. BusyBusy — payroll export and cash flow feature comparison
Related Blog Posts
- Construction Cash Flow Management — broader cash flow management strategy and tools
- Construction WIP Report — WIP billing position as inflow timing indicator
- Contractor Profit and Loss Statement — P&L as the annual context for the 13-week forecast
- Construction Retainage — retainage release timing as a major inflow event
- How to Negotiate a Construction Contract — payment terms, billing cycles, and retainage in contract negotiation
- Construction Bonds Guide — bonding capacity as a function of financial strength visible in the forecast